The best-performing S&P 500 sector outpaces the worst by an average of 46 percentage points annually. That performance gap isn’t random noise—it’s exploitable alpha sitting in plain sight while most portfolios collect static allocations and watch capital bleed into yesterday’s winners. Sector rotation isn’t about predicting economic futures or chasing momentum after the move is done. It’s about tracking where institutional capital is already flowing, positioning ahead of regime transitions, and extracting returns from predictable business cycle dynamics that systematically reprice entire industries. This isn’t beginner territory. We’re covering cycle phase mapping, leading macro indicators, implementation mechanics through ETFs and derivatives, quantitative multi-factor models, and the risk management protocols that separate tactical alpha from expensive churn. If you’re still buying and holding a balanced portfolio while sectors diverge 40-50% annually, you’re leaving serious money on the table.
The Economic Cycle Framework: Mapping Sectors to Market Phases
The S&P 500’s best-performing sector outpaces its worst by an average of 46 percentage points annually. That spread represents the difference between portfolio stagnation and compounding capital at rates that meaningfully alter wealth trajectories. Sector rotation isn’t about chasing momentum—it’s about positioning capital ahead of predictable business cycle transitions where institutional flows systematically reprice entire industries.
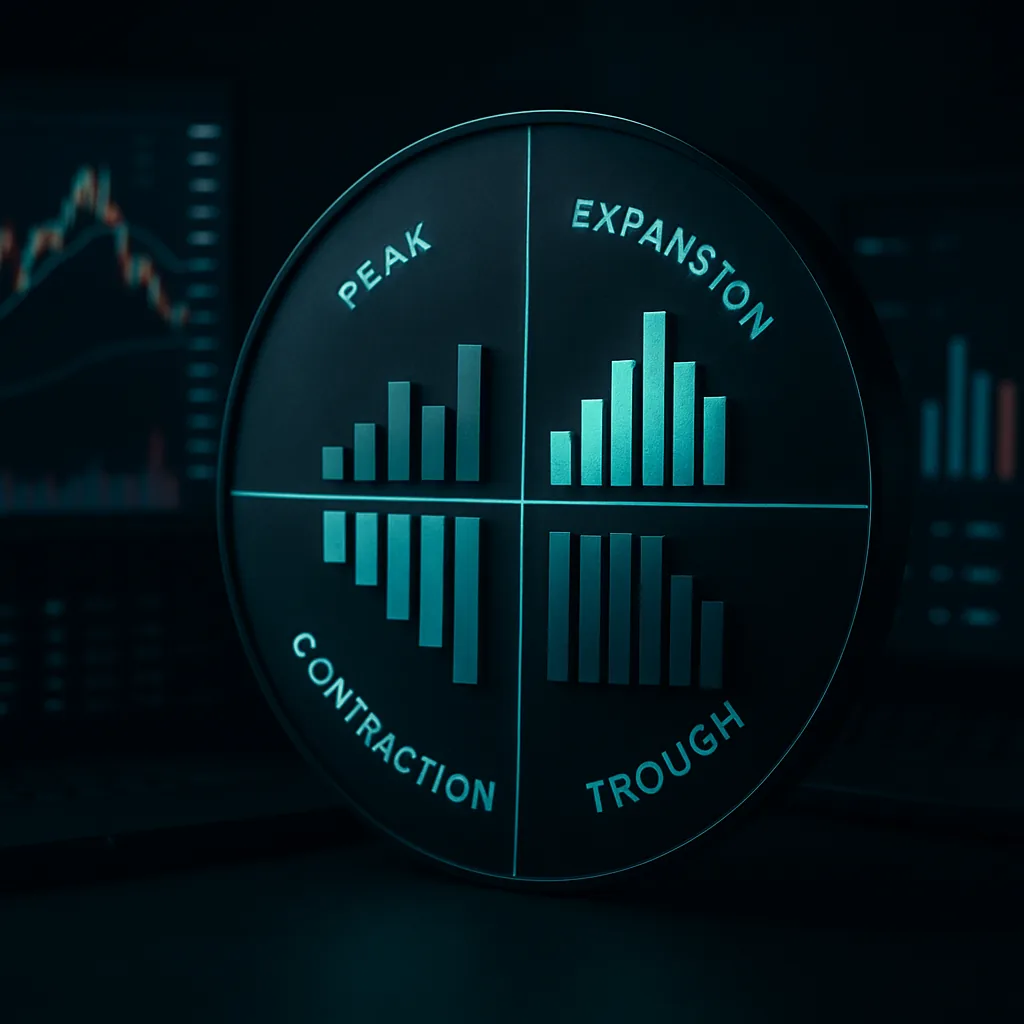
The traditional framework divides the economic cycle into four discrete phases, each with characteristic sector leadership patterns. During early-cycle recovery, credit spreads compress, unemployment peaks but begins declining, and GDP growth accelerates from depressed levels. Financials lead here because net interest margins expand while loan loss provisions normalize. Real estate and industrials follow, responding to lower borrowing costs and restocking demand. This phase rewards cyclical exposure before consensus acknowledges the recovery.
Mid-cycle expansion brings peak earnings growth velocity and maximum corporate confidence. Technology and consumer discretionary sectors dominate as businesses invest in productivity-enhancing capital expenditures and consumers leverage rising incomes into discretionary purchases. This is when markets price in the most optimistic forward multiples, and momentum strategies generate their strongest returns. Risk appetite peaks, volatility collapses, and defensive positioning gets systematically punished.
Late cycle and recession demand different capital allocation. Growth decelerates, capacity constraints emerge, and central banks tighten monetary policy to contain inflation. Investors rotate defensively into utilities, healthcare, and consumer staples—sectors with inelastic demand curves and stable cash flows that maintain earnings during economic contraction. These aren’t growth engines; they’re capital preservation vehicles that outperform through relative stability when cyclical sectors experience earnings compression.
Sector Characteristics and Cycle Sensitivity
Sector behavior during cycle phases stems from fundamental sensitivity to interest rates, GDP growth, and consumer confidence. Financials exhibit high leverage to interest rate curves and credit cycle positioning. A 100 basis point shift in the yield curve can alter bank profitability by 8-12% through net interest margin expansion or compression. Technology sensitivity centers on future earnings discounting—higher rates compress present values of distant cash flows, explaining why duration-like tech exposure corrects violently during monetary tightening.
Consumer discretionary tracks disposable income growth and employment trends with approximately 18-month leads to GDP inflection points. Industrials respond to capital spending cycles and inventory restocking, making them coincident indicators of manufacturing activity. Energy demonstrates commodity price sensitivity that often inverts traditional cycle logic—it can lead during late-cycle inflation or lag during deflationary recoveries.
Defensive sectors exhibit negative beta to economic acceleration. Utilities carry regulated revenue streams with bond-like characteristics, performing inversely to growth expectations and interest rate movements. Healthcare demand remains relatively constant regardless of GDP—people don’t defer cancer treatment during recessions. Consumer staples demonstrate the lowest earnings volatility of any sector, with 10-year standard deviation of quarterly earnings growth approximately 60% lower than consumer discretionary.
Why Traditional Rotation Patterns Break Down
Theoretical sector rotation assumes synchronized global business cycles, stable correlations between macro indicators and sector performance, and rational capital flows responding to changing economic conditions. Reality delivers none of these consistently.
Monetary policy distortions create regime changes that invalidate historical patterns. Zero interest rate policies and quantitative easing from 2009-2021 compressed volatility, extended cycle phases, and created persistent growth-over-value tilts that made traditional rotation signals unreliable. Financials underperformed for a decade despite economic expansion because negative real rates destroyed traditional banking profitability models.
Structural shifts in sector composition render backward-looking analysis increasingly problematic. The technology sector of 2024 bears little resemblance to 2004—it now includes cloud infrastructure with utility-like recurring revenue, making it simultaneously a growth play and defensive positioning. Classifying Amazon or Microsoft using traditional sector rotation frameworks misses their hybrid characteristics across multiple economic sensitivities.
Globalization and supply chain complexity mean U.S. sectors respond to foreign business cycles with unpredictable lags. A semiconductor company classified as “technology” might actually represent leveraged exposure to Chinese manufacturing activity, European auto production, and Taiwanese foundry capacity utilization—none of which correlate cleanly with U.S. GDP growth.
The framework provides a conceptual map, not a mechanical trading system. Capital markets anticipate cycle transitions 6-9 months ahead of economic data confirmation, requiring leading indicators beyond the cycle itself. Sector rotation works when you recognize which phase is ending, not which phase you’re currently in.
The 11 GICS Sectors: Performance Drivers and Capital Flow Dynamics
The S&P 500’s 11 GICS sectors aren’t just organizational buckets—they’re distinct asset classes with radically different performance drivers, correlation patterns, and sensitivity profiles. Understanding what actually moves each sector gives you an edge that generic asset allocation can’t touch.
Energy responds to crude oil supply shocks, OPEC production decisions, and geopolitical instability—not broad economic growth. Materials tracks industrial metal prices, construction activity, and emerging market infrastructure demand. Industrials leverages capital expenditure cycles, freight volumes, and manufacturing PMIs. Consumer Discretionary thrives on employment strength, consumer confidence, and disposable income growth, while Consumer Staples offers defensive stability with minimal economic sensitivity.
Health Care operates in its own regulatory universe, driven by FDA approvals, Medicare reimbursement rates, and demographic aging trends rather than GDP fluctuations. Financials live and die by the yield curve—steepness drives net interest margins for banks, while credit expansion fuels loan growth. Flat or inverted curves crush financial performance regardless of headline economic data.
Information Technology exhibits extreme interest rate sensitivity due to long-duration cash flow profiles; when discount rates rise, high-growth tech multiples compress violently. Communication Services blends growth and defensive characteristics, influenced by advertising spend (cyclical) and subscription revenue (stable). Utilities function as bond proxies with regulated returns, making them hypersensitive to rate movements. Real Estate combines leverage exposure (mortgage rates) with property fundamentals and REIT-specific tax treatment.
Capital doesn’t flow randomly between these sectors. It follows shifting expectations about growth, inflation, monetary policy, and risk appetite—variables that change dramatically across market regimes.
Cyclical vs. Defensive Sector Characteristics
Cyclical sectors amplify economic swings. When GDP accelerates, sectors like Consumer Discretionary, Industrials, Materials, and Energy outperform through operating leverage—fixed costs get spread across higher revenue, margins expand aggressively. Technology rides growth expectations and multiple expansion during liquidity-rich environments.
Defensive sectors—Consumer Staples, Health Care, Utilities—deliver consistent earnings regardless of economic conditions. People buy toothpaste in recessions. Electricity demand stays stable. These sectors underperform during expansions but preserve capital during contractions. Financials occupy middle ground, cyclical in credit quality but defensive through dividend yields.
The performance spread matters enormously. From 1990 to 2020, the best-performing sector beat the worst by an average of 46 percentage points annually. That’s not statistical noise—it’s the difference between portfolio stagnation and compounding wealth.
Interest Rate Sensitivity Across Sectors
Rate changes trigger divergent sector reactions that catch lazy portfolio managers off guard:
- Utilities and Real Estate: Negative duration exposure. Rising rates crush valuations as investors discount cash flows at higher rates and migrate to bonds offering competitive yields without equity risk
- Financials: Positive rate sensitivity through steeper yield curves. Banks borrow short and lend long; curve steepness directly translates to net interest margin expansion
- Technology: Severe rate sensitivity concentrated in high-growth, long-duration names. A 100 basis point rate increase can compress forward multiples by 15-20% in unprofitable growth stocks
- Energy and Materials: Rate-insensitive, commodity-driven performance. Oil prices override discount rate changes; copper demand from China matters more than Fed policy
- Consumer Staples and Health Care: Modest negative rate sensitivity offset by defensive earnings stability. Flight-to-quality flows during rate volatility can override valuation pressure
Understanding these dynamics transforms sector rotation from theoretical framework into executable strategy. You’re not guessing which sectors might outperform—you’re following capital as it responds to quantifiable macro catalysts.
Leading Indicators and Rotation Signals: Reading the Macro Tea Leaves
The real money isn’t made when rotation becomes obvious—it’s made 90 to 120 days before the financial press starts writing about it. By the time Bloomberg runs a feature on the defensive rotation into utilities, you’re already late. Successful sector rotation requires reading forward-looking indicators that telegraph economic regime shifts before they crystallize in earnings reports and backward-looking fundamental data.
Yield Curve Analysis for Cycle Positioning
The 10-year minus 2-year Treasury spread remains the single most reliable recession predictor, with inversion preceding all seven U.S. recessions since 1969. When this spread inverts—short-term rates exceeding long-term rates—defensive rotation typically begins within 6 to 18 months. The 2006 inversion gave you until late 2007 to rotate out of financials and into healthcare and consumer staples before the market acknowledged what fixed income traders already knew.
Watch the curve’s slope, not just inversion. A steepening curve from deeply inverted levels often signals the early stages of recovery, favoring financials, industrials, and materials before economic data confirms the turn. The 2020 rapid steepening from March lows provided a textbook entry signal for cyclical sectors while traditional recession indicators still flashed red.
PMI (Purchasing Managers’ Index) data for both manufacturing and services offers real-time economic activity readings with 30 to 60 day lead time over official GDP releases. Readings above 50 indicate expansion; below 50 signals contraction. Divergences between manufacturing and services PMI reveal which economic engines are driving growth and which sectors will capture that expansion.
Momentum and Relative Strength Metrics
Relative strength analysis strips away market-wide beta to isolate which sectors are actually attracting capital. Calculate the ratio of sector ETF price to SPY price and plot it over 13 and 26 weeks. When XLF/SPY crosses above its 26-week moving average while the yield curve steepens, financials are entering an institutional accumulation phase regardless of headlines.
The challenge: leading indicators provide 3 to 6 month forward visibility but generate false signals during volatile transition periods. The yield curve inverted briefly in 2019 without triggering recession. PMI can whipsaw around the 50 threshold. Confirmation through price action—sustained relative strength breakouts, volume patterns, and breadth expansion within the sector—separates actionable rotation signals from statistical noise. Use macro indicators to identify candidate rotations, then wait for technical confirmation before deploying capital.
Implementation Vehicles: ETFs, Leverage, and Derivatives
Sector-specific ETFs now control over $200 billion in assets, transforming rotation strategies from institutional-only positioning into retail-accessible tactical plays. The XLK (Technology Select Sector SPDR) alone trades $2-4 billion daily, offering tighter spreads than many individual large-cap stocks. Expense ratios for vanilla sector funds typically range from 0.10% to 0.40%, making frequent rotation mechanically feasible without management fees obliterating alpha.
Vanilla Sector ETFs vs. Leveraged Products
Standard sector ETFs track their underlying indices with minimal tracking error—typically 5-15 basis points annually for liquid funds. The XLE (Energy), XLF (Financials), and XLV (Healthcare) provide straightforward exposure with bid-ask spreads under 0.05% during market hours. These vehicles suit multi-week to multi-quarter rotation horizons where you’re positioning for macro regime shifts rather than intraday volatility exploitation.
Leveraged sector products—2x and 3x daily reset ETFs—amplify returns but introduce path dependency that destroys capital during choppy, range-bound markets. A sector that oscillates ±2% daily can produce negative returns in both the underlying index and its 3x leveraged counterpart over a two-week period due to daily rebalancing mathematics. The SOXL (3x semiconductor bull) famously lost 40% during a period when its underlying index was flat, purely from volatility decay. These instruments work for conviction-driven, trend-following plays with tight stop-losses, not buy-and-hold rotation strategies.
| Vehicle Type | Expense Ratio | Tracking Error | Optimal Holding Period | Primary Risk |
|---|---|---|---|---|
| Vanilla Sector ETF | 0.10-0.40% | 5-15 bps annually | Weeks to quarters | Sector-specific drawdown |
| 2x Leveraged ETF | 0.75-0.95% | High (path-dependent) | Days to 2 weeks | Volatility decay, liquidation |
| 3x Leveraged ETF | 0.95-1.10% | Very high | Intraday to 1 week | Extreme volatility decay |
| Sector ETF Options | Bid-ask spread | N/A | Expiration-dependent | Time decay, liquidity gaps |
Options Strategies for Rotation Positioning
Options on liquid sector ETFs enable capital-efficient rotation with defined risk parameters. A 30-delta call spread on XLF costs 15-20% of the capital required for outright shares while capturing similar upside if financials rally 8-12% over the next quarter. This structure frees capital for simultaneous positions across multiple sectors, increasing diversification without margin exposure.
Diagonal spreads—selling near-term premium against longer-dated long calls—extract theta while maintaining directional exposure to rotation themes. If you’re positioning for a late-cycle energy outperformance, buying 90-day XLE calls and selling 30-day calls against them reduces net cost by 30-40% while preserving participation in sustained trends.
The friction costs matter more than most rotation literature admits. Active rebalancing every 2-4 weeks generates short-term capital gains taxed at ordinary income rates, potentially surrendering 35-40% of gross alpha to the IRS. Bid-ask slippage on $50,000 sector ETF trades averages $25-75 per round-trip, seemingly trivial until you’re executing 15-20 rotations annually. These transaction costs establish a minimum performance hurdle of 150-200 basis points annually before rotation generates net outperformance versus static allocation.
Quantitative Rotation Models: Multi-Factor Approaches
Single-factor rotation strategies collapse under real-world market conditions. A momentum-only approach gets whipsawed during volatility regime changes. Value-only models trap capital in deteriorating sectors for years. The solution isn’t abandoning quantitative frameworks—it’s stacking multiple factors with asymmetric weighting to create confirmation filters that separate signal from statistical noise.
Factor Weighting and Signal Construction
Multi-factor rotation models synthesize momentum, value, quality, and macro variables into composite scoring systems. Momentum typically commands 40-50% of total weighting because trend persistence represents the most robust documented anomaly in sector rotation—capital flows create self-reinforcing cycles that last quarters, not weeks. A standard construction might allocate 45% to 12-month relative strength, 25% to valuation metrics (P/E and P/B ratios relative to historical sector norms), 20% to quality indicators (ROE, debt-to-equity, earnings stability), and 10% to macro variables (yield curve slope, credit spreads, PMI readings).
The critical insight: rotation signals require confirmation from multiple factors before capital deployment. A sector showing strong momentum but deteriorating quality metrics and extreme valuations generates conflicting signals—sophisticated models wait for alignment across at least three factors before initiating position changes. This confirmation threshold dramatically reduces false signals during transitional market regimes when single indicators whipsaw violently.
Sector rotation is fundamentally about tracking capital flows, not predicting economic futures. The institutional money moves 90-120 days before consensus catches up, and your edge lies in reading the leading indicators—yield curve dynamics, relative strength breakouts, PMI divergences—that telegraph regime shifts before they become obvious. But successful implementation demands more than signal identification. You need disciplined execution through appropriate vehicles, realistic expectations about transaction costs eating 150-200 basis points annually, and honest assessment of the strategy’s limitations.
Rotation strategies work during clear regime transitions—early recovery into cyclicals, late cycle into defensives, monetary tightening out of duration-sensitive sectors. They underperform badly in sideways, momentum-driven, or policy-distorted markets where traditional cycle logic breaks down. The 2010-2020 period punished mechanical rotation as QE and ZIRP extended the mid-cycle phase for a decade, making growth-over-value the only trade that mattered.
Treat sector rotation as tactical overlay within diversified portfolios, not a standalone strategy. Position sizing should reflect inherent timing uncertainty—even the best models generate 30-40% false signals during volatile transitions. The 46 percentage point annual spread between best and worst sectors represents genuine alpha opportunity, but capturing it requires combining macro awareness, technical confirmation, cost discipline, and the intellectual honesty to recognize when market conditions don’t favor rotation at all. Most portfolios would benefit from modest tactical tilts of 5-10% based on clear cycle signals rather than aggressive sector concentration bets that introduce uncompensated timing risk.
Leave a Reply